Stablecoin payouts, explained for people who've done pay-by-bank
How cross-border stablecoin payments work, where they beat wires, and the four compliance, FX, off-ramp and reconciliation questions to answer first.
 Image created with AI.
Pay-by-bank changed how customers pay once bank rails felt native. Customers stopped hunting for a card number and started tapping their bank. Nobody wrote a memo about it. The rail got good enough, and the old way started to feel like friction.
Businesses paying suppliers, creators, and contractors across borders are at that same point with stablecoins. The transfer itself is the easy part. The hard part is everything around it, and that is where most of the work lives.
A quick definition first. A stablecoin is a type of cryptocurrency pegged to an asset, usually a national currency such as the US dollar, so its value doesn’t swing wildly (Stripe). I’ll say “stablecoin” throughout, and “payout” for a cross-border payment from a business to someone it owes.
This piece walks through how a stablecoin payout actually moves money, where it beats a wire, and the four questions every team asks before it goes live.
The flow in three steps
A cross-border stablecoin payment looks like one action on a dashboard. Underneath, it is three steps, and each one has a different owner.
- USD in. The sender’s money sits in a dollar balance at a regulated institution.
- Stablecoin in transit. That balance is converted into a dollar-pegged stablecoin, sent on a blockchain, and received by a provider on the other side.
- Local currency out. The provider converts the stablecoin into the recipient’s currency and credits a local bank account.
The diagram below shows five boxes because the on-ramp and off-ramp are the conversions at each end of step 2 and step 3. Providers such as Bridge describe this as orchestration: sending, receiving and converting between fiat and stablecoin.
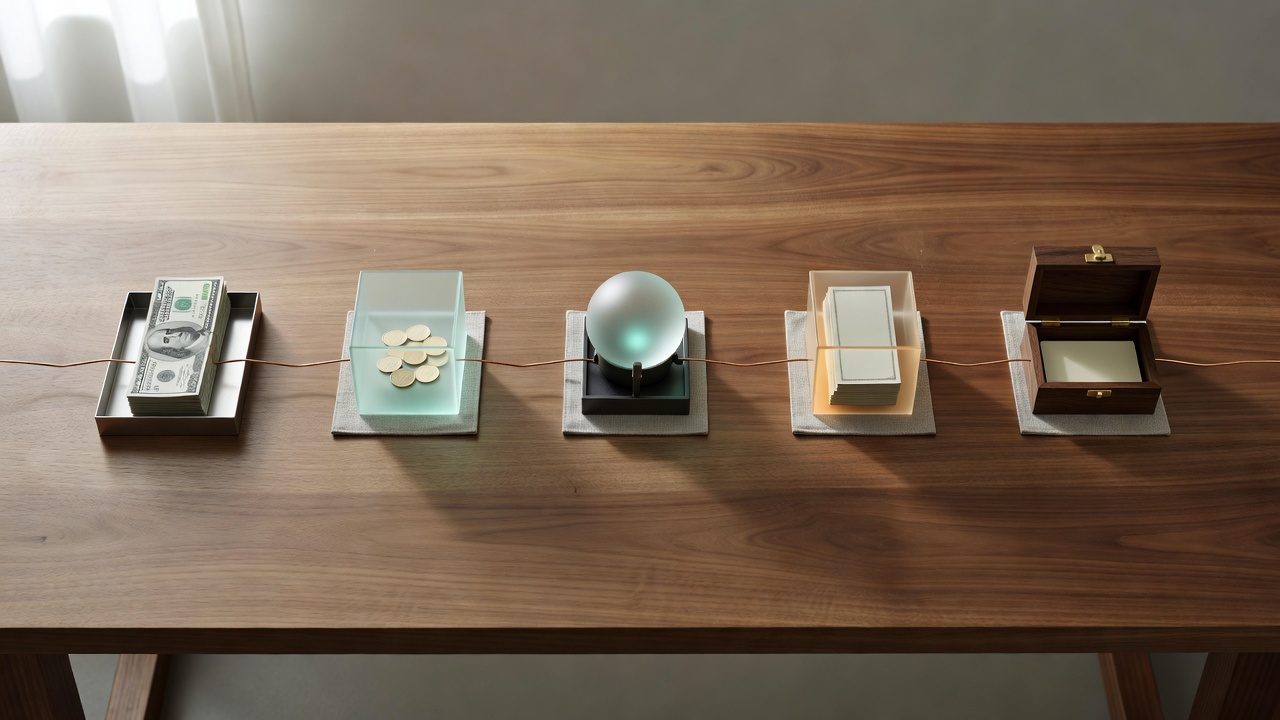 Image created with AI.
The diagram is the whole model. Once you can name who holds the money at each box, most of the design questions answer themselves.
Where it beats wires and local rails
The honest case for stablecoin payouts is narrower than the hype, and it is strongest in three places:
- Settlement speed. On a public blockchain, settlement happens within seconds or minutes, and the transfer is final (Stripe). A cross-border wire can pass through the originating bank, a messaging network, possibly a correspondent bank and the receiving bank, and domestic processing at the receiving end can add one to two business days (Cross River).
- Availability. Stablecoin settlement runs continuously and is not subject to banking hours, weekends or holidays. Local banking infrastructure for the final fiat credit still runs on business-day schedules, which is why the off-ramp section below matters (Cross River).
- Fewer hops. Each intermediary bank is another point where a payment can stall, get reviewed, or lose information.
Be fair about where wires still win. Large-value transfers and low-volume corridors with thin liquidity are often cheaper and simpler through a traditional bank. A stablecoin route that saves two days on a payment that only happens twice a year is not a win. It is a new system to maintain.
The question to ask is not “is this faster?” It is “for which payments, on which corridors, at what volume, does this route pay for its own operational overhead?”
 Image created with AI.
The four questions every team asks
Once a team agrees the economics are interesting, the conversation shifts to four questions. These are the ones that decide whether a launch goes smoothly.
1. Compliance: who checked whom?
Every transfer needs KYC on both ends, meaning the sender and the recipient have been verified. Above certain thresholds, regulators require the sending and receiving institutions to pass along identifying information about the originator and beneficiary. This is often called the travel rule, and the threshold depends on where you operate. In the US, it applies to transfers of $3,000 or more under 31 CFR 1010.410(f), which FinCEN applies to convertible virtual currency. In the EU, Regulation 2023/1113 sets no general minimum for covered crypto-asset transfers (Bridge developer guide). Bridge also notes the rule generally does not apply when funds never leave its custody and no on-chain transfer goes to an outside wallet. On Nov 9, 2026, FinCEN and the Federal Reserve withdrew a 2020 proposal to cut the US threshold to $250 (Federal Register). Globally, FATF’s revised standard sets USD/EUR 1,000 for peer-to-peer cross-border payments, with name, address and date of birth, effective by the end of 2030. Check the current rules for each corridor you plan to serve. (Source: FATF, “FATF updates Standards on Recommendation 16 on Payment Transparency,” 18 June 2025.)
The operational consequence is simple to state and hard to build: you need an audit trail that follows a payout from the first KYC check to the final bank credit, and it has to survive when the asset moved through a blockchain that does not know your internal account IDs.
This is where I think the real moat sits. The transfer is a commodity. The team that can prove, to a regulator or an auditor, exactly who sent what to whom, and why, is the team that gets to keep operating.
2. FX: where does the conversion really happen?
A stablecoin payout typically involves two conversions. The on-ramp converts USD to the stablecoin. The off-ramp converts the stablecoin to local currency. Each conversion carries a spread, and the spreads are not always visible in the same place.
Ask your provider three questions in writing:
- Where does each conversion happen, and at what rate?
- What is the all-in spread, including any fees that are not shown as fees?
- How long is the rate locked between quote and settlement?
If you cannot answer those for your own corridor, you do not yet know whether the route is cheaper than the wire you are replacing.
3. Off-ramps: can the money actually land?
An off-ramp is only as good as the bank account it credits. Some corridors have deep local banking access. Others have settlement windows that open only a few times a day, or banking partners that impose their own review on inbound funds.
The questions here are operational. Which banks can receive the payout? When do they settle? What happens when a transfer lands outside the window? A stablecoin route that is instant on-chain but waits until Tuesday at the local bank is not instant. Map the full timeline before you promise anyone a time. The revised standard also requires institutions to adopt tools that protect against fraud and error, such as verifying a recipient’s banking information. (Source: FATF, “FATF updates Standards on Recommendation 16 on Payment Transparency,” 18 June 2025.)
4. Reconciliation: one payout, one invoice
This is the question finance teams underestimate most. Traditional payments produce a bank reference that matches an invoice. A stablecoin payout produces a blockchain transaction hash, a conversion record, and a bank credit, often from three different systems.
Matching them takes deliberate design. You need a stable internal reference that travels with the payout, a record of each conversion and its rate, and a way to tie an on-chain event back to the invoice it paid. Without that, month-end close becomes a manual hunt through block explorers and CSV exports.
If your reconciliation process cannot answer “which invoice did this on-chain transfer pay, and at what effective rate?” in a few minutes, the payout is not ready for production.
 Image created with AI.
What to check before you build
If you are considering this for your own team, start with a short checklist. None of these are technical decisions. They are operational ones, and they belong to people outside engineering.
- Licensing in each corridor. Confirm which entities you need, and which provider already holds them, in every country you plan to pay.
- Custody model. Know who holds the stablecoin while it is in transit, under what agreement, and what happens if that party fails.
- Holding and hedging policy. Decide whether you hold stablecoins between steps, for how long, and whether you hedge exposure by timing the off-ramp.
- Treasury ownership. Name the person who owns the balance, the rate risk, and the exception queue. If the answer is “engineering,” that is a warning sign.
Each item on that list is a decision that will show up in an audit eventually. It is cheaper to make it deliberately on day one.
The question I’d like you to answer
On Nov 17 I argued that stablecoin payouts are an operations problem, not a technical one, and that compliance is the moat (LinkedIn post). The four questions above are where that argument gets tested.
Where does your team’s pain sit right now: in compliance evidence, in FX visibility, in off-ramp timing, or in reconciliation? I suspect the answer tells you more about whether stablecoin payouts make sense for you than any speed benchmark will.
Sources are linked inline. Product descriptions reflect public Stripe and Bridge documentation, and regulatory points reflect FATF publications, checked on the publish date.